If your policy hasn’t been reviewed in years, you could be paying too much. Consumer Reports found that 30% of drivers switched insurers in the past five years and those who changed saw a median annual savings of $461. That shows loyalty can cost more than it helps.
Many people don’t know their provider offers driver monitoring tools. Smartphone tracking apps cut a median $120 from annual premiums for drivers who enrolled. Small actions like that add up fast.
Compare current coverage and rates with other top insurance companies. Look for discounts, and ask your insurer about monitoring programs and safe-driver credits. If you want a quick guide with practical tips, check this helpful resource: how to save money on car.
Key Takeaways
- Thirty percent of drivers switched companies in five years to lower costs.
- Switching insurers produced median savings of about $461 per year.
- Driver-monitoring apps can reduce premiums by a median of $120.
- Review your policy every few years to keep rates competitive.
- Ask insurers about discounts and automated programs before renewing.
Understanding Your Current Insurance Policy
Start by reading your declarations page so you clearly see what your policy covers and what it excludes. This short review helps you spot missing protections and overlaps that affect your annual premiums.
Common Types of Coverage
Comprehensive coverage protects your vehicle from theft, vandalism, weather damage, and collisions with animals like deer. Liability pays for another person’s injuries or property damage that you cause.
Medical payment coverage helps pay medical bills for you and passengers after an accident, regardless of fault. Check limits and exclusions so you know what each feature actually pays.
Factors Affecting Your Annual Premium
Your insurance company checks reports and scores that act like credit reports. These predict how risky a driver is and influence insurance costs.
- Driving record and past accidents
- Type and age of vehicle—high-performance cars often cost more
- Chosen deductible — higher deductible lowers premiums but raises out-of-pocket risk
- State rules and company-specific cover limits
“Reviewing coverage every few years can prevent surprise bills after a claim.”
| Coverage | What it pays | Typical effect on premiums |
|---|---|---|
| Comprehensive | Theft, vandalism, weather, animal collisions | Moderate increase |
| Liability | Bodily injury and property damage to others | Main cost driver |
| Medical Payments | Injury treatment for driver and passengers | Small to moderate |
For a practical checklist and a short policy review guide, see how to review your coverage.
The Best Ways to Save Money on Car Insurance Through Comparison
Shopping several insurers at once reveals large gaps in price and coverage that many drivers miss.
The U.S. Bureau of Labor Statistics reports premiums rose 84% from 2020 to 2025, so rates have changed a lot in recent years.
To find real savings, shop around and compare quotes from multiple insurance companies. Look beyond sticker price.
When you review offers, make sure you compare coverage limits, deductibles, and annual premiums so comparisons are fair.
Check state insurance department tools and nonprofit ratings for consumer satisfaction and complaint history.
“Comparing quotes is one of the most effective ways to combat rising costs.”
Also verify an insurer’s financial strength. A low premium is only useful if the company pays claims reliably.
| What to Compare | Why it matters | Where to check | Quick tip |
|---|---|---|---|
| Coverage limits | Determines payout size after a claim | Policy declarations page, state site | Match like-for-like |
| Deductible | Impacts out‑of‑pocket cost and premiums | Quotes and insurer documents | Raise only if you can afford it |
| Annual premium | Real yearly cost after discounts | Multiple company quotes | Check total cost, not monthly only |
| Company strength | Claims payment and long-term reliability | Ratings agencies, state regulators | Prefer financially stable insurers |
Bundling Policies for Maximum Savings
Insuring your home and vehicle with the same company can unlock meaningful price breaks. Bundling often reduces paperwork and makes billing simpler for a household.
Combining Home and Auto Coverage
Linking auto and homeowners policies typically produces a noticeable discount. Our analysis found that combining these two types of coverage results in an average discount of 13 percent on your total insurance bill.
If you rent, ask your provider about bundling renters coverage with your car policy. Many insurers also offer reduced rates for insuring multiple vehicles, motorcycles, boats, or RVs under one policy.
- Check coverages: Confirm the bundle includes the protections you need.
- Compare totals: Make sure the combined price beats separate policies from different companies.
- Ask about extra discounts: Some firms reward multiple policies with additional credits.
| Bundle Type | Typical Benefit | Tip |
|---|---|---|
| Home + Auto | ~13% average discount | Verify limits match your needs |
| Multiple vehicles | Policy-level savings | Include motorcycles or boats when possible |
| Renters + Auto | Similar discounts for non-owners | Good option if not a homeowner |
“Consolidating policies often leads to real annual savings and simpler account management.”
Adjusting Your Deductibles to Lower Premiums
Raising your deductible is a quick lever you can use to cut recurring premiums while keeping the same coverage.
A deductible is the fixed amount you pay out of pocket before your insurer covers a claim. Typical personal deductibles start at several hundred dollars and can go up to a couple thousand per incident.
For collision and comprehensive coverage, ask your agent about increasing the deductible. Insurance companies usually lower rates when you accept a higher deductible because you take more initial risk.
Before you change a policy, run the numbers. Calculate potential yearly savings against the extra costs you might pay after an accident. That helps decide if the switch makes sense for your finances.
- Request higher deductibles on collision and comprehensive to reduce premiums.
- Remember the deductible applies per incident; you pay it each time you file a first-party claim.
- After you meet the deductible, the insurer pays for the remaining repair costs.
“A higher deductible lowers premiums but increases what you carry in your pocket if an accident happens.”
For a short policy checklist and calculation tips, see how to review your coverage.
Leveraging Loyalty Discounts with Your Current Insurer
Long-term customers often qualify for modest discounts and special protections not listed on standard quotes.
Staying with the same insurance company can yield an average loyalty discount of about 3 percent. That may not seem huge, but it adds up when combined with other credits.
Ask your agent whether you qualify for accident forgiveness, diminishing deductibles, or milestone rewards for five, 10, 15, or 20 years with the company. These perks often apply only if you remain claim-free.
“A small loyalty credit and accident forgiveness can be worth more than a slightly lower initial quote from a new insurer.”
| Perk | What it does | When it helps |
|---|---|---|
| Loyalty discount (~3%) | Reduces annual premium | After several years with same company |
| Accident forgiveness | Prevents a single claim from raising rates | If you have a clean record for years |
| Diminishing deductible | Lower out-of-pocket cost each claim-free year | Best for long-term, careful drivers |
Before you switch, compare those loyalty perks with quotes from new insurers. If you want a quick checklist for policy review, see this guide.
Improving Your Driving Record for Better Rates
Keeping tickets and accidents off your record will pay dividends when insurers set your rates.
Safe driving helps maintain lower premiums. A single speeding ticket can raise your renewal by about 32 percent, though exact changes vary by company.
Play the long game: avoid at-fault crashes and citations. Over time, a clean driving record signals lower risk and leads insurers to offer steadier rates.
- Drive defensively and obey speed limits to reduce the chance of a citation.
- Keep a safe following distance and avoid distractions to lower crash risk.
- If you have a ticket, ask your agent how it will affect your policy before you renew.
“Avoiding tickets and accidents is the best long-term strategy for steady premiums.”
Regular reviews matter. For a short checklist on monitoring trends and cleaning up minor issues, see our quick policy review guide at policy review tips.
Taking Defensive Driving Courses
Completing an approved defensive driving course often earns a measurable discount from many insurers.
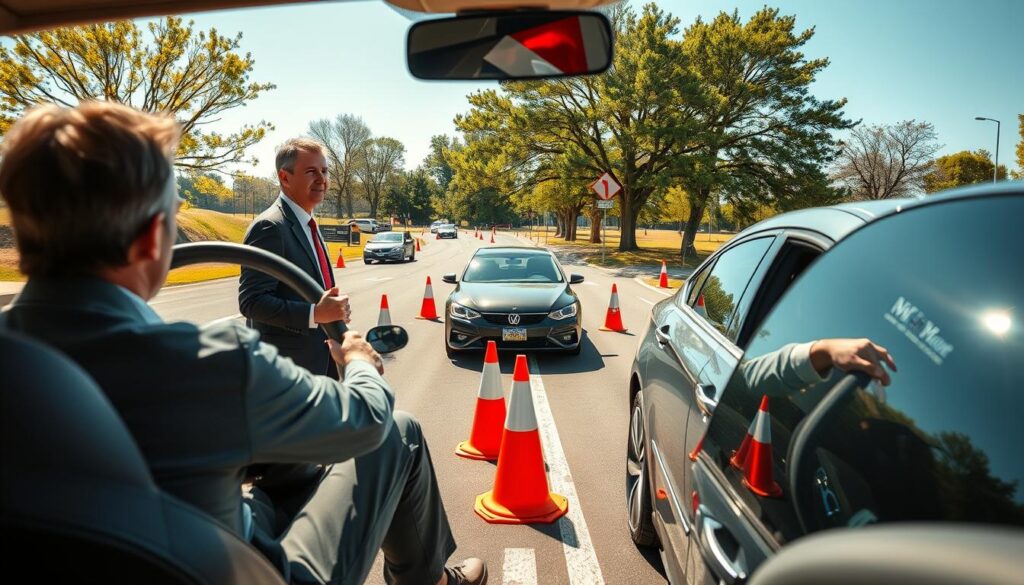
Courses typically take six to eight hours and are available online or in person. Many insurance companies accept them and grant a 5%–15% annual premium reduction.
The discount usually lasts two to three years. After that you can retake the driving course to renew the credit.
- Some states offer mandated discounts for older drivers, often at ages 50, 55, or 60 and up.
- Nonprofits like the National Safety Council and AARP list low‑cost online courses, often under $40.
- Completing a course shows an insurer you invest in safer driving, which may help avoid future accident claims.
“Confirm acceptance with your insurance company before enrolling so the course counts toward your discount.”
Quick tip: Ask your agent if the specific driving course qualifies for a credit and whether it affects your deductible or coverage limits.
Optimizing Your Vehicle Choice and Safety Features
A model’s repair costs, theft risk, and safety equipment all influence how insurers set your rates. Picking a vehicle with lower replacement and repair costs can cut annual coverage expenses for many drivers.
Impact of Vehicle Age and Model
Age and type matter. A two-year-old luxury minivan often carries lower premiums than a brand-new high-performance sports car that costs more to repair and replace.
Classic or antique vehicles may need specialty policies, so check with an agent before buying one. Always confirm how a vehicle’s value and age influence your premium.
Benefits of Advanced Safety Equipment
Cars with automatic emergency braking, lane-keeping assist, or built-in anti-theft systems can qualify for lower insurance rates.
- Example: Geico offers up to a 23 percent discount on comprehensive coverage for vehicles with anti-theft systems.
- Confirm whether aftermarket devices are accepted; not all equipment qualifies for discounts.
- Before purchase, ask your insurer how specific safety features will affect future premiums and coverage.
“Choosing a vehicle with strong safety features often reduces costs and improves protection for drivers.”
Utilizing Telematics and Usage-Based Programs
Opting into a driving-monitoring app gives you a chance to show safe habits and earn a discount over time. These programs log speed, braking, mileage, and time of day. An insurer then analyzes the data to judge real risk rather than rely only on demographics.
Many drivers volunteer for usage-based tracking through a phone app or a plug-in device. Safe behavior often leads to lower premiums while risky patterns can raise your insurance rates.
- Enrollment is usually optional; ask your insurance company how long the test period lasts.
- Confirm privacy rules and how your auto data is stored and shared.
- Use feedback from the program to improve habits and reduce the chance of an accident.
“Telematics lets drivers prove safety and unlock personalized discounts.”
Before you sign up, check what the company reports and how long discounts last. Participating can lead to real savings and better-matched coverage over time.
Paying in Full and Electronic Payment Options
Paying your full premium at the start of a policy term often trims your annual bill noticeably. Many insurers reward upfront payment with an average 7% reduction in total costs.
If a lump-sum isn’t possible, set up electronic funds transfer (EFT) from your checking account. EFT commonly yields about a 3% credit and reduces the risk of missed payments.
Going paperless typically adds a small 1% discount. These options do not change your coverage or deductible. They simply lower how much the company charges for billing and handling.
- Pay in full: ~7% average savings on the total policy cost.
- EFT: ~3% average discount and fewer late fees.
- Paperless billing: ~1% extra credit for electronic documents.
“Automating payments helps avoid late fees and keeps your coverage active.”
Before you switch methods, make sure your insurer does not add a credit card surcharge that wipes out these discounts. Small billing changes are an easy way for a driver to lower annual insurance costs without touching coverage limits.
Reviewing Coverage Needs Based on Life Events
Major life events can shift your insurance needs; check your coverage soon after any big change.
Moving to a new town or state often changes your risk profile and your rates. Update your address and ask about local rules that affect minimum limits.
Starting a new job or retiring may change daily miles. That affects how much protection you really need. Lower mileage might let you trim collision coverage, while a longer commute could require higher limits.
If you haven’t reviewed your policy in a while, you might be paying for cover you no longer use. Conversely, not updating details could leave you underinsured after a serious crash.
- Review your coverage yearly or after any major life change.
- Contact your insurance company to check discounts and adjust limits.
- Keep policy data current so protection matches your lifestyle and budget.
“Keeping your insurance information current is a proactive way to stay protected at the right price.”
Consulting with Insurance Professionals
An experienced advisor can translate complex policy language into practical guidance for your situation. Talking with a licensed agent saves time and helps you compare coverage and rates across multiple companies.
Members Insurance Advisors uses a consultative approach to match credit union members with flexible options. Agents research multiple A-rated carriers and present quotes that match your lifestyle.
- Agents help you shop around and confirm the discounts insurance companies offer.
- They explain how driving record, safety features, and state rules affect your auto policy and costs.
- An agent can advise whether a defensive driving course or changing your deductible protects your pocket after a collision or accident.
Working with a pro gives a clearer picture of the number and types of coverage you need. That guidance makes it easier to choose an insurer and keep rates steady over the years.
“A good agent helps drivers find tailored coverage and uncovers discounts they might miss.”
Conclusion
A short annual check helps keep your coverage aligned with life changes and costs. Review limits, discounts, and any new safety features on your vehicle. Small updates can prevent gaps and surprise bills.
Maintain a clean driving record and combine policies where it makes sense. Use telematics, defensive driving courses, and billing options to capture available credits.
Keep an eye on your rates and make a habit to shop around periodically. These steady habits help you manage costs while keeping the protection you need on the road.